| The Federal-Aid Highway Act of 1956 – commonly known as the National Interstate and Defense Highways Act – triggered the construction of countless highways throughout the United States. Those newly-constructed highways were then able to take Americans from their offices in American cities to the suburbs. The suburbs…where there is just less density. Paving the way – literally, and figuratively – for suburban housing demand. Coupled to the building of suburban homes. Those were (and are) larger homes. Larger than homes that could be built in the denser American cities.  Ten years – 41,000 miles – $25 billion. This is what the Highway Act consisted of. $25 billion and 41,000 miles of American highways. Let’s use Kansas City as an example. Interstate 435 in the Kansas City Metro Area traces its origin back to the year 1965. I-435 could take a Kansas Citian out of Kansas City, Missouri – where a family might live in a smaller home – to Overland Park, Kansas. And in Overland Park, Kansas, larger homes have been built, can be built and will continue be built. There was just more space in Overland Park, Kansas to build larger homes. More space than there was – in 1965 – in center city Kansas City, Missouri. And one can get there – to Overland Park, that is – by taking I-435. So I-435 is and has been a catalyst in regard to why larger homes would be built, can be built, will continue to be built and are built in the Kansas City Metro Area suburbs. It is, just as it was…the highway.Like |
Author: Ted Ihde
Ted is a real estate broker, a real estate developer as well as co-CEO of Team With Heart.
Highways…the suburbs…the suburbs…highways: Interconnected reliance.
The Federal-Aid Highway Act of 1956 – commonly known as the National Interstate and Defense Highways Act – triggered the construction of countless highways throughout the United States. Those newly-constructed highways were then able to take Americans from their offices in American cities to the suburbs. The suburbs…where there is just less density. Paving the way – literally, and figuratively – for suburban housing demand. Coupled to the building of suburban homes. Those were (and are) larger homes. Larger than homes that could be built in the denser American cities.
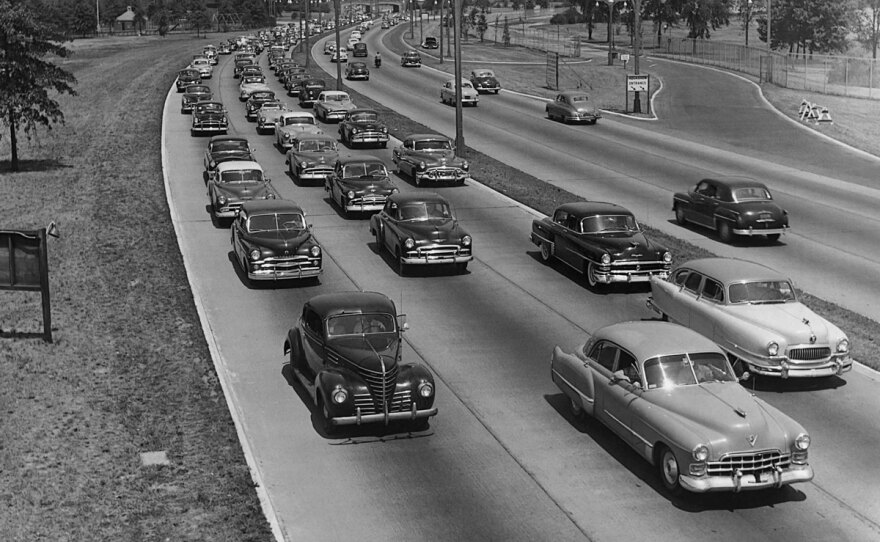
Ten years – 41,000 miles – $25 billion. This is what the Highway Act consisted of. $25 billion and 41,000 miles.
Let’s use Kansas City as an example.
Interstate 435 in the Kansas City Metro Area traces its origin back to the year 1965. I-435 could take a Kansas Citian out of Kansas City, Missouri – where a family might live in a smaller home – to Overland Park, Kansas. And in Overland Park, Kansas, larger homes have been built, can be built and will continue be built.
There was just more space in Overland Park, Kansas to build larger homes. More space than there was – in 1965 – in center city Kansas City, Missouri. And one can get there – to Overland Park, that is – by taking I-435. So I-435 is and has been a catalyst in regard to why larger homes would be built, can be built, will continue to be built and are built in the Kansas City Metro Area suburbs.
It is, just as it was…the highway.
Liquor and early-20th Century KC: a test case in how legislating morals might not work
The National Prohibition Act, known as the Volstead Act or the Valentine Act, was passed to carry out the 18th Amendment prohibition of the manufacture, the transportation and the sale of alcohol.
It was the outlawing of intoxicating beverages. While the Act outlawed alcohol (for awhile) the Act simultaneously facilitated a birth of subcultures. Nightlife in Kansas City during the Prohibition era is one such example.
During the Prohibition era, Kansas City became a wide open town. “Paris of the Plains.” A springboard for bootleg booze, speakeasies, loose morals and gambling.
This early-20th Century subculture in Kansas City – fueled by the sale of illegal alcohol – was perfectly coupled to an already-thriving jazz scene. Converging to push the “nightlife needle” in Kansas City up just as prohibition, on paper at least, was supposed to push the alcohol-enhanced “nightlife needle” down.
Kansas City during the Prohibition era. An example for what can occur when there is a convergence of ideals taken from perspectives which are not aligned with societal intentions.
Prohibition had been something like a Puritanical goal coming out of Washington D.C. Washington D.C. was not Kansas City.
The idea of prohibition turned out to be no match for the all-night jazz sessions speakeasies which sprang up in Kansas City.
Prohibition. That idea didn’t work out so well in Kansas City.
Long, long ago the United States implemented a pro-immigrant federal real estate policy
The Preemption Act of 1841 enabled American settlers to claim up to 160 acres of federal land at a cost of $1.25 an acre.
According to provisions of the Act, land acquirers needed to be either, A) 21 years old, or B) head of household.
Furthermore, through the Preemption Act, an immigrant who intended to become a United States citizen – yet who would not have been a citizen of the United States at the time they acquired their land through the Preemption Act -was eligible to acquire their land at the same cost of $1.25/acre.
In the mid-19th Century, United States citizens who acquired land through the Preemption Act, as well as immigrants who intended to one day become United States citizens who acquired land through the Preemption Act, were required to make improvements to their property and to utilize the property they acquired as a personal residence for at least five years.
Circumstances, Timing, and Policy. Or a lack thereof?
It can credibly be argued that opportunities for Americans to build wealth through the acquisition of real estate has usually been based upon, 1) circumstances, and 2) timing.
Minus, 1) favorable circumstances, and 2) good timing, is (or was) an American just outta luck in regard to real estate? Due to different reasons, for many – long, long ago, and still today – that answer, unfortunately, was and is, “YES.”
So what role can, should or will government take on with regard to creating more opportunities for generational wealth building through the ownership of real estate? Remember, as a “game-changer,” HUD was created 59 years ago…in 1965. A long time ago.
Going back…hundreds of years before the formation of HUD, what role did our government play when real estate was sought out? In the earliest stages of our American set-up.
During the 1600’s, a select portion of those residing in what would go on to become the American colonies – those who aspired to “own” land for themselves, that is – ventured out, and found themselves a piece of land. They claimed that land. They then “owned” that land. And there you have it. Notwithstanding, this was land “ownership” – for some – without a deed being recorded. Notwithstanding, this was land “ownership” without the issuance of title insurance. Notwithstanding, this was land “ownership” which went into effect without the use of a mortgage.
During the 17th Century, in what would go on to become the United States, when one wanted land, one could often just travel a few miles north. Or south. Or east. Or west. Outside of a settled area, that is. Find some barren land. Land that had not yet been claimed. Then, proceed to claim that unsettled land. Circumstances permitted.
So a notable portion of our early “eligible” American settlers didn’t see value in buying land from someone else. Nor was there a need to.
Circumstances. Timing.
When the United States is short millions of new homes – as we are today – and when there is no substantive national policy being spoken of which can work towards addressing our very real housing problem (in an election year, for that matter) do we just leave this all to “Mr. Market,” and say, “Well…it’s just, 1) circumstances, and 2) timing.”
That’s kinda what we’re doing…
A land bank is ok for Kansas City, but New York is different. Oh really?
Of the one million or so investor-owned residential homes in the State of New York, it has been estimated that in excess of 3% of these investor-owned properties sit vacant or abandoned. Say, between 30,000 and 35,000 homes. Vacant. Abandoned. Non-performing.
In New York, municipalities which can establish land banks include a) cities, b) villages, c) towns, and d) counties.
Here is how it works…
The New York municipality first establishes an entity to function as what is known as a “foreclosing governmental unit.” The foreclosing governmental unit operates within guidelines established through local laws, local ordinances and local resolutions. The laws, ordinances and resolutions outline parameters by which the city, village, town or county – i.e.: the “municipality” – is able to establish procedures which enable the municipality to function as the foreclosing governmental entity. I.e.: as the land bank.
Oversight and governance for New York land banks is the responsibility of land bank boards of directors.
Opportunity Zones: 7 years ago, the “Why?” in the “Why!”
In 2017, Opportunity Zones were created through the Tax Cuts and Jobs Act of 2017. That same year, the Minority Business Development Agency (the MBDA) conducted a study which focused upon differences in, A) access to financing, and B) financing costs, for businesses owned by White business owners, as compared to businesses owned by minority business owners.
The same year Opportunity Zones were created – in 2017 – the MBDA reported that the average loan provided to White-owned businesses totaled $310,000. And how about for minority-owned businesses? Financing provided to minority-owned businesses – according to the MBDA study – dropped substantially. To $149,000. That $149,000 financing amount…less than half of the amount which had been made available to White business owners.
OK, so how about the cost-of-credit?
According to the 2017 MBDA study, the average interest rate paid by minority-owned businesses had been 7.8%. For White-owned businesses? The cost-of credit was significantly lower. It was 6.4%.
So the 2017 MBDA study showed how White business owners paid less for the money they borrowed than minority business owners paid. And they were able to borrow quite a bit more money too.
In looking at findings in the 2017 MBDA study, one may have thought, it seemed to be rather expensive to not be White in business.
Opportunity Zones are merely one building block. In a building. A building that has a lot more floors that need to be built. Long before the building is even close to being complete.
Mom focused on your foundation and your grades. When you build a new home, become mom.
Mom intended for you to build your life upon a solid foundation…with good grades. Foundation. Grades. Mom. New home construction. Different contexts. Same message.
Land grading is the structuring of the land surface on which your new home will be built. Land grading for a buildable residential lot is applicable to that lot’s slope. For your new home build, it is important to ensure that a proper slope is added to the surface of your residential lot. In order to attain your sought after “grade.”
An ideal slope for your new home build is one where the land surface located on the outer perimeter of your home’s foundation descends away from the home’s footprint. This descent is important because land grading will ultimately determine where rainwater – as well as where runoff water from your roof – will flow to once the construction of your home is complete.
Opportunity Zone: an economic development tool that allows people to invest in distressed areas in the United States
Many news pieces as of late featuring Opportunity Zone proponent- devout Christian – South Carolina Senator Tim Scott. So a little bit here about one reason Senator Tim Scott cares so deeply about Opportunity Zones: ACCESS TO – OR A LACK THEREOF – FINANCING FOR BUSINESSES OWNED BY BLACK AMERICANS
According to a Federal Reserve report I read a few years ago, Black business owners apply for bank financing at a slightly higher rate than White business owners do. Yet, according to the same report I read, just over fifty per-cent of Black business owners are turned down for business financing. The turn-down rate for White business owners? It’s about half of that rate – it’s about 25%.
Ok, so how about the turn-down rate for business financing applied for by Asian American business owners? The turn-down rate for business financing applied for by Asian American business owners had been – according to the report I read – just about 35%.
How about for Hispanic business owners? According to that same report, the turn-down rate for business financing applied for by Hispanic business owners had been a little under 40%.
Access to financing – or a lack thereof – for American businesses which are owned by Black Americans… No one purports to proclaim that there is any sort of quick fix to inequality. This being said, support for – and continued interest in – Opportunity Zones has multiple facets applicable to “upside.” Tim Scott, is right.